Rethinking Modern Banking: How Mashreq NEO PLUS Is Redefining the Digital Banking Experience One Year After Its Launch
Chiraag Jogia, Senior Vice President – Global Head of Customer Value Management at Mashreq NEO, reflects on how the proposition is simplifying wealth-building by bringing banking, saving, investing and financial insights into one accessible, personalized digital experience.
You're reading Entrepreneur Middle East, an international franchise of Entrepreneur Media.
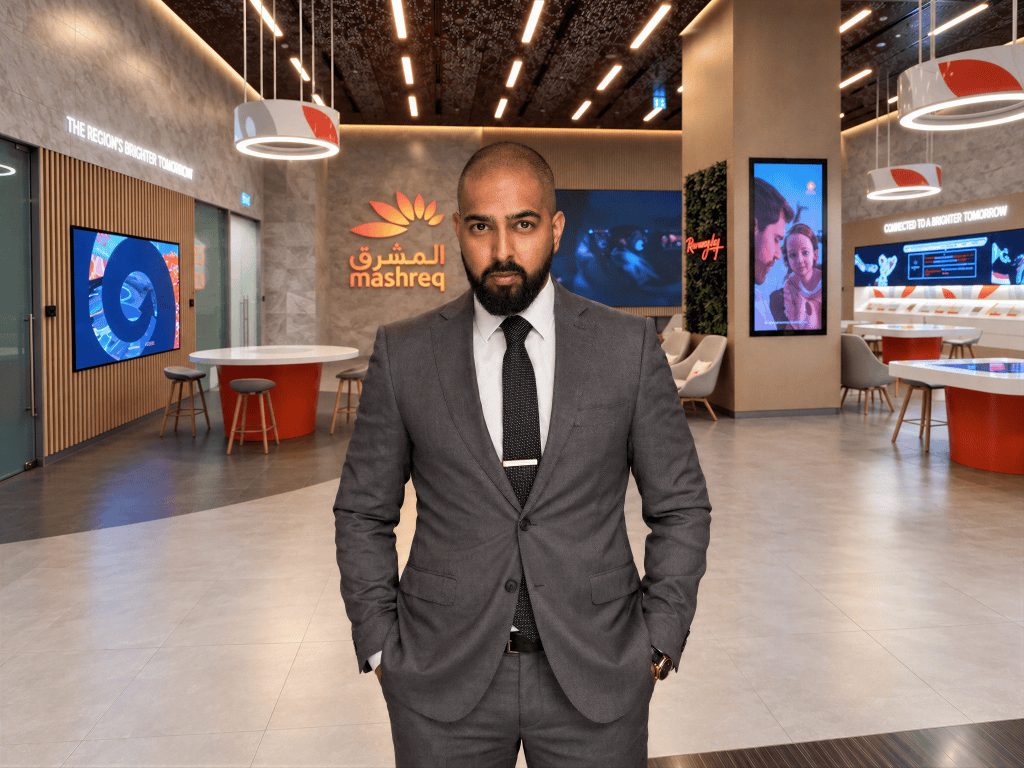
In July 2025, Mashreq’s digital banking platform, Mashreq NEO, launched NEO PLUS: a fully digital banking proposition for customers earning a monthly salary of at least AED10,000 or maintaining a balance of AED 50,000. Combining fee-free everyday banking, saving and investing within a single app, the NEO PLUS Saver Account offers a 6.25% annual interest rate for qualifying salary customers and a 5% rate for non-salary customers who meet the balance requirement. Customers can also begin investing from US$1, receive 10 free trades per month, or access managed portfolios starting from US$100, with the broader proposition designed to make wealth-building more accessible and straightforward. At the heart of all this technical jargon, however, is a simple yet ambitious vision. “To us it was clear that we wanted to create the UAE’s leading banking proposition for the mass-affluent segment,” declares Chiraag Jogia, Senior Vice President – Global Head of Customer Value Management at Mashreq NEO. “But before defining what that proposition should look like, we spent time listening to customers and understanding what they genuinely wanted from their bank. Two messages came through consistently: help me grow my money, and make it simple. Those insights became the foundation for NEO PLUS. We wanted to move beyond everyday transactions and create a proposition that delivered meaningful value while making it easier for customers to save, invest and build their wealth. Just four months after setting that ambition, we launched NEO PLUS.”
That attention to detail has ultimately held NEO PLUS in good stead in the one year it’s been operational in the UAE. For starters, it has seen double-digit year-on-year growth in deposits and revenue, alongside growth in customer Net Promoter Score [a widely used measure of customer satisfaction and loyalty, based on the question: How likely are you to recommend this company, product or service to someone else?] “For us, commercial growth and customer value go hand in hand,” says Jogia. “The growth we have seen in deposits and revenue is a result of more customers choosing NEO PLUS, engaging more deeply with the proposition and increasingly trusting Mashreq NEO with their primary banking relationship. The improvement in customer Net Promoter Score is equally important because sustainable growth depends on creating experiences that customers genuinely value and are willing to recommend.”
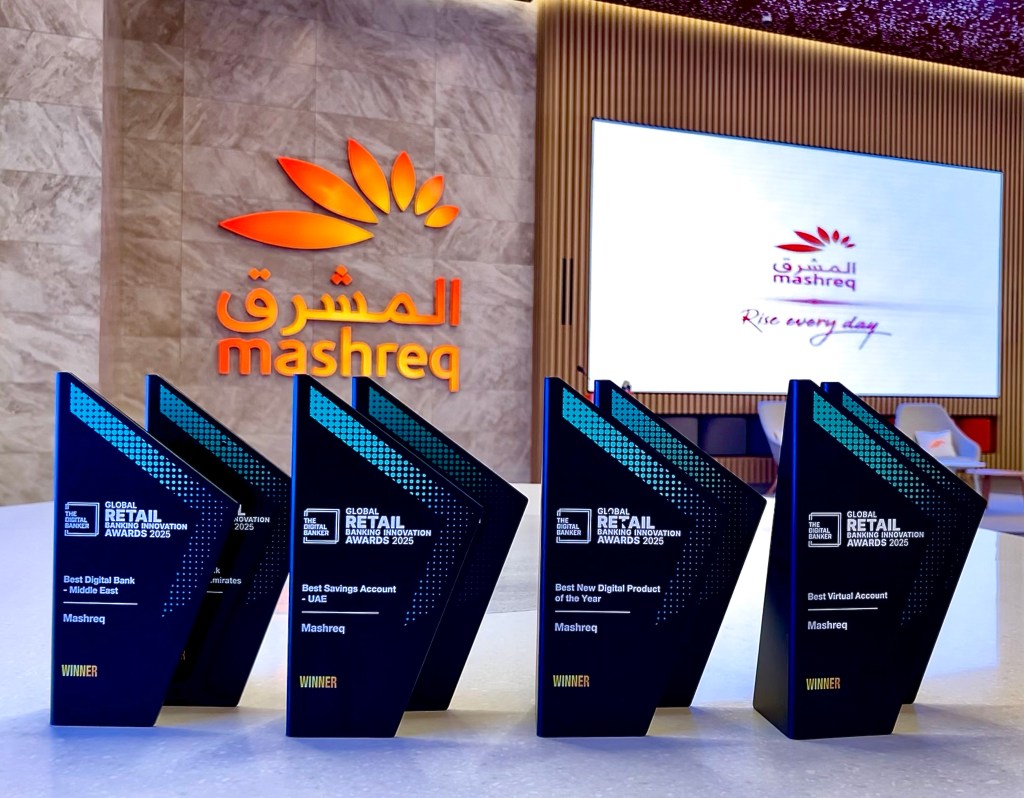
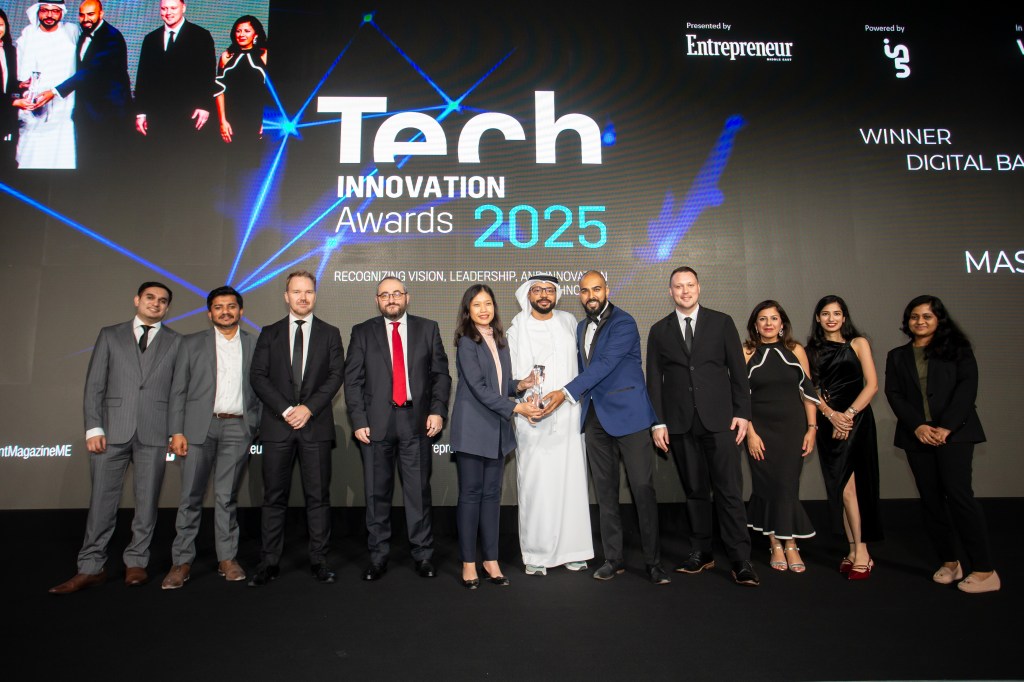
That momentum has also translated into industry recognition, with Mashreq NEO securing six titles at The Digital Banker’s Global Retail Banking Innovation Awards 2025. Three went specifically to NEO PLUS, for Best New Digital Product of the Year, Best Savings Account and Best Virtual Account. “What makes this particularly meaningful is that NEO PLUS was never designed as a single product or benefit,” Jogia shares. “It was built as an integrated experience, with each element playing a different but important role. The mobile banking experience keeps managing money simple, our savings and investment propositions help customers make their money work harder, and the broader proposition brings everything together in a way that is accessible, rewarding and relevant. Industry recognition therefore provides valuable external validation that we are building something differentiated.”
Here, Jogia is quick to circle the conversation back to the bank’s customers, stating that the recognition received from the users is the ultimate nod of approval. “We see that in the way customers are engaging more deeply with the proposition, using more of its capabilities and continuing to share positive feedback with us. So, yes, awards are an important proof point, but they are not the destination. What matters is whether the different parts of the proposition work together to create meaningful value and a better experience for customers. The combination of industry recognition, customer engagement and customer feedback gives us confidence that NEO PLUS is moving in the right direction.”
But beyond the numbers, awards and customer response lies the question of what gap NEO PLUS was designed to fill in the first place. For Jogia, the answer lies in what Mashreq NEO saw as an underserved space between traditional premium banking and existing digital offerings. “When we looked at the UAE market, we felt there was a clear gap for the mass-affluent customer,” he explains. “Traditional premium banking propositions often came with high entry thresholds, complex qualifying criteria, or fees for packaged benefits that customers did not necessarily want or use. At the same time, many digital banking propositions made everyday transactions easier but did not go far enough in helping customers save, invest and grow their wealth. We wanted to remove those trade-offs.”
That meant rethinking what “premium” banking itself should entail. “For us, premium banking should not mean complexity or paying for a bundle of benefits that may not be relevant,” Jogia adds. “It should mean delivering meaningful value and giving customers simple, accessible tools to manage their everyday finances and grow their money.”
At the core of NEO PLUS’ growth trajectory, however, is a perhaps less evident but significant factor: its attempt to narrow the gap between having access to wealth-building tools and actually understanding how to use them. “In the mass-affluent segment, building wealth is rarely just about having access to another financial product. More often, it is about understanding your current position, building confidence and developing positive habits over time,” Jogia explains. “That starts with better visibility. For example, Mashreq Money Insights can help NEO customers understand where their money is going, see their income and spending more clearly, and identify recurring commitments through features such as Activity Tracker and Subscription Tracker. The aim is to turn financial data into simple, actionable information.”
“The next step is helping customers turn that understanding into action. Features such as Auto-Save allow customers to put their savings on autopilot, making it easier to save consistently and build positive habits. The goal is to help each customer take the next best step in their financial journey, whether that means understanding their spending, building a regular savings habit, or feeling ready to begin their investing journey.”
For Jogia, continuing to listen to what the NEO PLUS customers have to say has been paramount in fine-tuning the service’s efficiency. “Even right after the launch, we did not stay still – constantly taking feedback and evolving the proposition, introducing new capabilities that deepen customer value and make managing and growing money simpler,” he adds.
Amid the lessons learned through this process, Jogia notes that some stood out more than others. “Perhaps the most important lesson from the first year is that customers are looking for more than an attractive rate or a collection of benefits,” Jogia says. “They want a deeper banking relationship that helps them understand their money, make better decisions and take meaningful action. One of the strongest indicators of that is the growth we have seen in customers choosing NEO PLUS for their primary banking needs, including moving their salary to Mashreq NEO. That represents more than product adoption. It demonstrates trust and shows that customers see value in bringing their everyday banking, saving and investing together in one relationship.”
“We are also seeing clear evidence that better visibility can lead to better financial decisions,” Jogia shares. “Four in five customers engage with Money Insights to better understand their finances, and one in five take an action directly as a result of the insights they receive. We have also seen strong growth in the use of features such as Auto-Save.”
Jogia notes that this has been particularly encouraging among customers aged 18 to 30. “Rather than waiting until they have accumulated significant wealth, they are using digital tools and insights to start building better habits today. For me, that is one of the clearest measures of the proposition’s impact. It is not only helping customers access products. It is helping them become more engaged, better informed and more confident in how they manage and grow their money.”
As such, Jogia believes that these insights and behaviours give his team a great starting point to continue improving the proposition as NEO PLUS enters its second year.
“As we enter the second year, our ambition remains the same as when we began this journey 18 months ago: to make a step change in banking for the mass-affluent segment. Commercially, that means continuing to grow the customer base, while also deepening relationships across everyday banking, saving and investing. We want NEO PLUS to become an increasingly important part of customers’ financial lives, rather than simply being a proposition they use for one particular benefit. From a customer perspective, success means seeing more people take greater control of their finances, build long-term financial resilience and make confident progress towards their individual goals. It means creating greater value from their everyday banking and developing more relevant, personalised ways to support those goals. The customer feedback we have received, together with the behavioural trends we are seeing, gives us confidence that we are building something special. The first year has established strong foundations, but there is much more potential ahead. Our focus now is to build on that momentum, continue listening to customers and evolve NEO PLUS in ways that deliver stronger commercial performance by creating even greater value and better financial outcomes for the people we serve.”
‘TREP TALK: Chiraag Jogia on what modern banking means for UAE customers
New Beginnings: “Many people arrive in the country at a pivotal stage in their lives, whether they are beginning a new career, building a family or seeking new opportunities. As new residents, they may initially have limited visibility of their likely living costs, how best to manage their finances or where to begin when it comes to saving and investing.”
Simplifying Finance: “Customers want to manage their everyday finances, understand where their money is going and find ways to make it work harder, without having to navigate multiple providers or complicated processes. Bringing those needs together in one place is important, but what takes the experience over the line is keeping it simple.”
Evolving Expectations: “Customers increasingly expect their bank to do more than hold and move their money. They want greater transparency, more control and clearer value from the relationship. They are more conscious of the returns available on their savings, more open to beginning an investment journey and less willing to accept unnecessary complexity, high barriers or benefits that are not relevant to them.”
In July 2025, Mashreq’s digital banking platform, Mashreq NEO, launched NEO PLUS: a fully digital banking proposition for customers earning a monthly salary of at least AED10,000 or maintaining a balance of AED 50,000. Combining fee-free everyday banking, saving and investing within a single app, the NEO PLUS Saver Account offers a 6.25% annual interest rate for qualifying salary customers and a 5% rate for non-salary customers who meet the balance requirement. Customers can also begin investing from US$1, receive 10 free trades per month, or access managed portfolios starting from US$100, with the broader proposition designed to make wealth-building more accessible and straightforward. At the heart of all this technical jargon, however, is a simple yet ambitious vision. “To us it was clear that we wanted to create the UAE’s leading banking proposition for the mass-affluent segment,” declares Chiraag Jogia, Senior Vice President – Global Head of Customer Value Management at Mashreq NEO. “But before defining what that proposition should look like, we spent time listening to customers and understanding what they genuinely wanted from their bank. Two messages came through consistently: help me grow my money, and make it simple. Those insights became the foundation for NEO PLUS. We wanted to move beyond everyday transactions and create a proposition that delivered meaningful value while making it easier for customers to save, invest and build their wealth. Just four months after setting that ambition, we launched NEO PLUS.”
That attention to detail has ultimately held NEO PLUS in good stead in the one year it’s been operational in the UAE. For starters, it has seen double-digit year-on-year growth in deposits and revenue, alongside growth in customer Net Promoter Score [a widely used measure of customer satisfaction and loyalty, based on the question: How likely are you to recommend this company, product or service to someone else?] “For us, commercial growth and customer value go hand in hand,” says Jogia. “The growth we have seen in deposits and revenue is a result of more customers choosing NEO PLUS, engaging more deeply with the proposition and increasingly trusting Mashreq NEO with their primary banking relationship. The improvement in customer Net Promoter Score is equally important because sustainable growth depends on creating experiences that customers genuinely value and are willing to recommend.”
That momentum has also translated into industry recognition, with Mashreq NEO securing six titles at The Digital Banker’s Global Retail Banking Innovation Awards 2025. Three went specifically to NEO PLUS, for Best New Digital Product of the Year, Best Savings Account and Best Virtual Account. “What makes this particularly meaningful is that NEO PLUS was never designed as a single product or benefit,” Jogia shares. “It was built as an integrated experience, with each element playing a different but important role. The mobile banking experience keeps managing money simple, our savings and investment propositions help customers make their money work harder, and the broader proposition brings everything together in a way that is accessible, rewarding and relevant. Industry recognition therefore provides valuable external validation that we are building something differentiated.”

Aalia Mehreen Ahmed • Senior Features Editor, Entrepreneur Middle East
Entrepreneur Staff
Senior Features Editor at Entrepreneur Middle East and host of Anchored Echoes, with nearly seven... Read more