Etihad Credit Bureau Launches Credit Score 3i, Expanding Credit Risk Assessments from 24 to 36 Months
The model assesses financial obligations and repayment patterns over a longer period to provide a broader view of individuals’ credit behavior and support lenders’ risk assessments.
You're reading Entrepreneur Middle East, an international franchise of Entrepreneur Media.
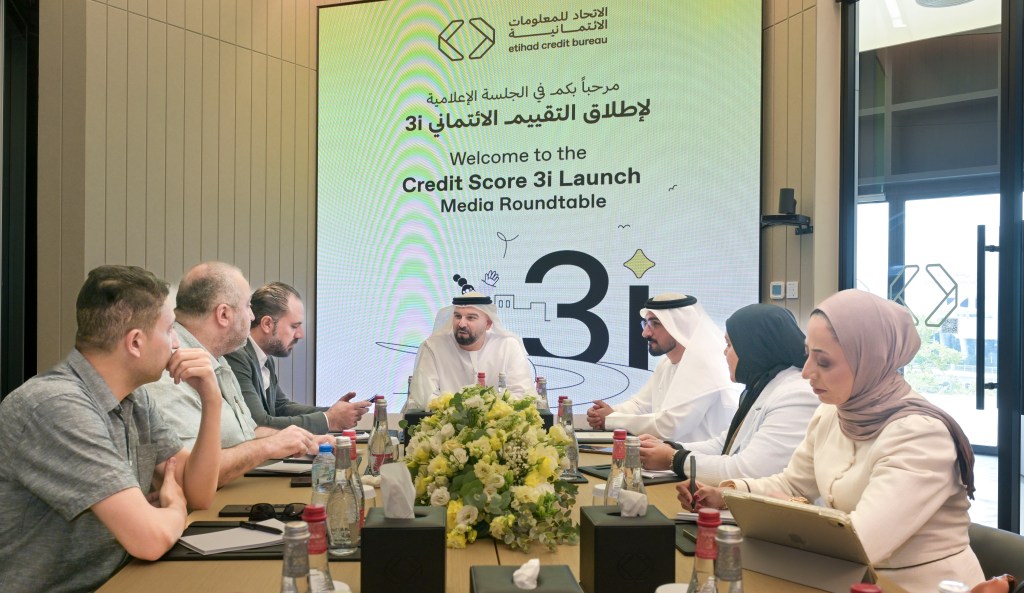
Etihad Credit Bureau, the federal entity responsible for providing credit information and data-driven analytics in the UAE, has launched Credit Score 3i, a new model that extends the credit assessment period from 24 to 36 months and expands coverage to eligible individuals with limited credit histories.
The model assesses financial obligations and repayment patterns over a longer period to provide a broader view of individuals’ credit behavior and support lenders’ risk assessments.
“The UAE continues to develop its financial and credit information ecosystem in step with economic and technological change,” H.E. Marwan Ahmad Lutfi, Director General of Etihad Credit Bureau, said. “Credit Score 3i advances the use of data and analytics to support more comprehensive credit risk assessments, strengthen financial sector efficiency and encourage responsible credit practices.”
It covers individuals with established credit histories, as well as eligible people who are new to credit or recent arrivals in the UAE with limited credit records.
The model introduces two scoring ranges: 300 to 850 for individuals with established credit histories and 300 to 650 for eligible individuals with limited histories.
Credit Score 3i may also reflect improvements in an individual’s credit behavior within six months after they settle defaults, depending on their subsequent repayment behavior, overall credit profile, and the model’s criteria.
However, an increase during this period is not guaranteed. New defaults or other negative developments may affect progress, requiring a further period of positive credit behavior before improvements are reflected in the score.
For banks, financial institutions and other authorized entities, including eligible fintech companies and digital platforms, the model provides additional credit information to support lending decisions and risk management.
Lending decisions remain subject to each institution’s policies and assessment criteria.
The launch comes as the bureau’s database and use of its services have expanded. As of September 2026, its database covered approximately 11.6 million individuals and businesses, 20.2 million active credit contracts, and 25.3 million active International Bank Account Numbers (IBANs).
The bureau issued more than 17 million credit reports and scores in 2025, compared with approximately 1 million in 2015. In 2026, it also expanded credit reporting to include buy now, pay later accounts and other short-term credit products, providing a broader view of individuals’ financial obligations.
Individuals can access their credit scores through the Etihad Credit Bureau website or its mobile app, subject to registration, identity verification, and applicable fees. The bureau encourages users to review their credit information regularly and check its accuracy.
RELATED: UAE Ministry of Finance Opens Second Retail T-Sukuk With 5.06% Profit Rate
Etihad Credit Bureau, the federal entity responsible for providing credit information and data-driven analytics in the UAE, has launched Credit Score 3i, a new model that extends the credit assessment period from 24 to 36 months and expands coverage to eligible individuals with limited credit histories.
The model assesses financial obligations and repayment patterns over a longer period to provide a broader view of individuals’ credit behavior and support lenders’ risk assessments.
“The UAE continues to develop its financial and credit information ecosystem in step with economic and technological change,” H.E. Marwan Ahmad Lutfi, Director General of Etihad Credit Bureau, said. “Credit Score 3i advances the use of data and analytics to support more comprehensive credit risk assessments, strengthen financial sector efficiency and encourage responsible credit practices.”

Entrepreneur Middle East Staff
Entrepreneur Staff